Inflation Expectations Hold Steady at Target as Yields Edge Up
MarketsFN Data Team
What is a breakeven rate?
The breakeven inflation rate equals the yield gap between a conventional Treasury and a TIPS of the same maturity. If the 10Y nominal yields 4.50% and the 10Y TIPS yields 2.00%, the 10Y breakeven is 2.50% — the level of average CPI at which an investor is indifferent between the two bonds. A higher breakeven signals stronger market inflation expectations.
Why three horizons?
The 5Y breakeven is most sensitive to near-term CPI prints and Fed policy. The 10Y breakeven blends short and long-run expectations. The 5Y/5Y forward looks only at years 5–10, stripping out near-term noise — it is the purest read on whether long-run inflation is anchored. The Fed watches the forward rate most closely.
The Fed's 2% target in breakeven terms
The Federal Reserve targets 2% PCE inflation, not CPI. Because CPI runs roughly 0.3–0.5 pp above PCE (different basket weights and housing costs), breakevens in the 2.2–2.5% range are broadly consistent with the Fed achieving its mandate. Breakevens above 2.5% signal markets doubting that 2% will be delivered; below 2.0% signals deflation or stagnation risk.
Real yields and monetary conditions
The 10Y TIPS yield is the "real" risk-free rate — what investors earn above and beyond inflation. Positive real yields make saving more attractive than spending or risk-taking: a tightening drag on the economy. Negative real yields (common in 2020–2022) were highly stimulative, driving asset prices and compressing credit spreads. The real yield is a direct gauge of monetary restriction.
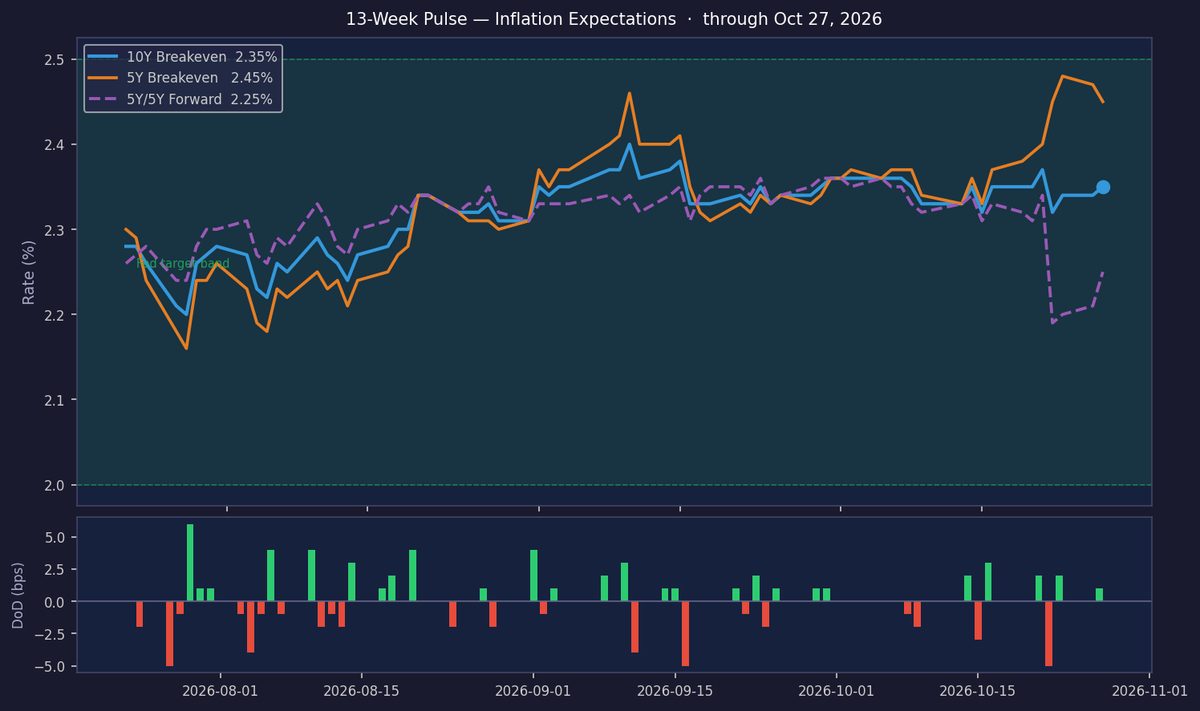
Inflation expectations remain anchored today, with the 10Y breakeven steady at 2.35% amid an ON TARGET regime. The daily uptick of 1 bp reflects muted market movement, consistent with the 3-month average of 2.32% and elevated historical percentile (75.2th). Investors appear broadly comfortable with the Fed's progress, as evidenced by the lack of meaningful divergence in near-term breakevens.
The 5Y breakeven (2.45%) continues to trade above the 10Y (2.35%), suggesting modest near-term inflation pressures, though the -10 bp term premium indicates no structural concerns. The 5Y/5Y forward (2.25%)—the Fed’s preferred anchoring metric—is stable but slightly below its 3-month average (2.32%), hinting at a mild drift lower. This bears watching, though it remains within a neutral range.

The 10Y real yield of 2.66% signals restrictive monetary conditions, as it exceeds the Fed’s estimated neutral rate. This is reinforced by the 6.23% nominal yield, reflecting elevated inflation compensation (3.57%) and tight policy. Real yields at these levels imply the economy is operating with meaningful policy restraint, likely tempering growth and inflation risks.
A regime shift from ON TARGET would likely require a sustained move in breakevens beyond the 2.20–2.50% range or a sharp reversal in the term structure (currently -10 bp). Key catalysts include the next CPI print or Fed communication challenging the soft-landing narrative. For now, the flat term premium suggests limited market urgency to reprice long-term inflation risks.
| Series | Latest | DoD | WoW | 10Y Rank | Freq. |
|---|---|---|---|---|---|
| 10Y Breakeven (T10YIE) | 2.35% | +1.0 bps | +0.0 bps | 75.2th pct | Daily |
| 5Y Breakeven (T5YIE) | 2.45% | -2.0 bps | +6.0 bps | 76.2th pct | Daily |
| 5Y/5Y Forward (T5YIFR) | 2.25% | +4.0 bps | — | 65.8th pct | Daily |
| 10Y Real / TIPS (DFII10) | 2.66% | +0.0 bps | — | — | Daily |
| 10Y Nominal (DGS10) | 6.23% | +0.0 bps | +24.0 bps | — | Daily |
| Term Premium (10Y−5Y be) | -10.0 bps | n/a | — | — | Derived |
| CPI YoY | 4.0% YoY (September 2026) | n/a | — | — | Monthly |
| Core PCE YoY | 3.0% YoY (August 2026) | n/a | — | — | Monthly |